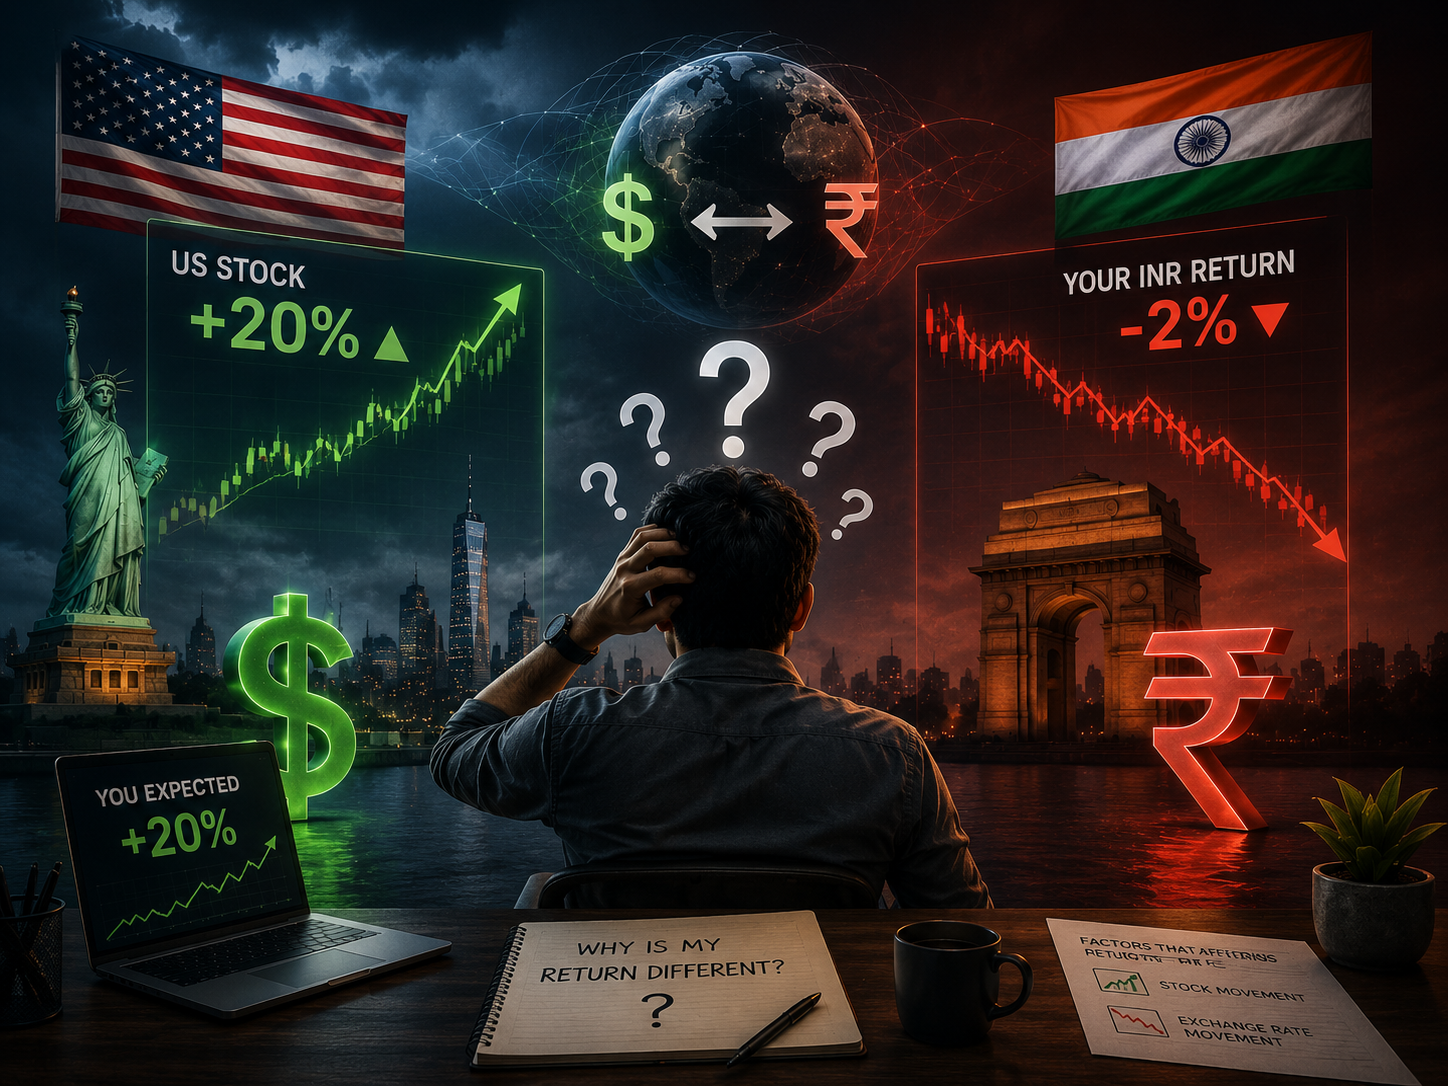
The stock went up. Your return didn't follow. Here's the missing piece: currency.
Imagine you are an investor in India.
You find a US company you really like. You research the business, study its financial statements, look at its valuation, and finally decide to invest.
A year later, you check your investment.
You are happy.
You made 20%.
Or did you?
The answer has nothing to do with the company.
It has to do with something happening thousands of kilometres away: the exchange rate.
When You Invest Abroad, You Are Making More Than One Bet
When an Indian investor buys a US stock, the obvious risk is the stock itself.
If the company performs well, its share price may rise. If the company disappoints, its share price may fall.
But there is another variable.
The Asset
Will the stock, bond, or property increase or decrease in value?
The Currency
What happens to the foreign currency relative to your home currency?
The investment is priced in US dollars, while the Indian investor ultimately measures wealth in Indian rupees.
That creates another source of return — and another source of risk.
This is why the return you see on a foreign stock exchange is not necessarily the return you experience in your own currency.
Let's Go Back to That 20% Gain
Suppose you invest in a US stock.
The stock rises by 20%.
| Investment | Return |
|---|---|
| US Stock | +20% |
Looks simple.
But now imagine that during the same period, the US dollar falls 15% against the Indian rupee.
The Mathematics Behind the Story
Assume you initially invest ₹100.
For simplicity, imagine ₹100 converts into exactly $1.
The stock rises by 20%.
So far, everything looks great.
But then the dollar loses 15% of its value against the rupee.
Not +20%.
| Component | Movement |
|---|---|
| US stock | +20% |
| US dollar vs INR | -15% |
| Final INR return | +2% |
The stock made 20%.
You made only 2% in rupee terms.
This is one of the easiest things to miss when investing internationally.
The Same Investment Can Produce Different Returns
Now imagine three investors buy exactly the same US stock.
Thinks in USD
Thinks in INR
Thinks in EUR
They own exactly the same stock.
Yet their realized returns can be completely different.
| Investor | Home Currency | Stock | FX Effect | Result |
|---|---|---|---|---|
| US | USD | +20% | None | +20% |
| India | INR | +20% | -15% | +2% |
| Europe | EUR | +20% | Depends on USD/EUR | Different |
Currency Can Also Work in Your Favor
Currency risk is not automatically bad.
The same force that can reduce your return can also increase it.
Suppose the US stock rises 20%, but this time the US dollar appreciates 10% against the rupee.
| Stock | USD Movement | Indian Investor |
|---|---|---|
| +20% | +10% | +32% |
| +20% | 0% | +20% |
| +20% | -15% | +2% |
Currency can therefore become an additional source of return or an additional source of loss.
It Works in the Other Direction Too
Now consider something even more interesting.
The US stock falls by 5%.
At the same time, the US dollar appreciates by 10% against the rupee.
The stock lost money.
But the currency helped the Indian investor.
| Stock | Currency | Combined Return |
|---|---|---|
| -5% | +10% | +4.5% |
A losing foreign stock can therefore still produce a positive home-currency return if the currency movement is favorable enough.
Why Does This Matter?
Global investing gives investors access to companies, industries and economies outside their home country.
It can also provide diversification.
But once you invest across borders, another layer of risk enters the portfolio:
Currency movements can have a meaningful impact on the return of foreign-currency investments.
Currency Risk Isn't Just About Stocks
The same principle applies to many international investments.
| Investment | Possible Currency Exposure |
|---|---|
| Foreign stocks | Equity return + currency movement |
| Foreign bonds | Bond return + currency movement |
| Foreign money-market assets | Interest income + currency movement |
| Foreign real estate | Property return + currency movement |
The asset class changes.
The currency problem remains.
So Should You Hedge the Currency?
Once investors understand currency risk, the natural question is:
This is where currency hedging enters the picture.
Investors can use instruments such as forward contracts, futures or options to manage their exposure to exchange-rate movements.
But hedging is not free.
It can involve transaction costs, financing effects, forward points, opportunity costs and other considerations.
| Approach | FX Exposure | Potential Benefit | Potential Drawback |
|---|---|---|---|
| Unhedged | High | Can benefit from favorable FX | FX can reduce returns |
| Partially Hedged | Moderate | Balances exposure and protection | More complex |
| Fully Hedged | Low | Reduces currency-driven volatility | Hedging costs and lost FX upside |
There is no universal rule saying every foreign investment should be fully hedged or completely unhedged.
The decision depends on the investor's objectives, risk tolerance, investment horizon, currency exposure and the cost of hedging.
The Bigger Lesson
When you buy a foreign stock, it is tempting to focus entirely on the company.
You study its revenue.
You study its margins.
You study its valuation.
You study its competitive advantage.
All of that matters.
But if you are a foreign investor, there is another number quietly moving in the background.
It can turn a 20% stock gain into a much smaller gain.
It can turn a modest stock return into a much larger one.
And in some situations, it can turn a positive investment return into a loss in your home currency.
When you invest internationally, you are not only investing in an asset. You are also taking exposure to the currency in which that asset is denominated — unless you hedge it.
One Final Question
The next time you see a headline saying:
Don't immediately assume that every international investor made 20%.
Ask one more question:
That single question can completely change the story of an investment.
What to Explore Next
Currency is only the beginning of international investing. The next questions are even more interesting:
- Why do currencies appreciate and depreciate?
- What determines the USD/INR exchange rate?
- How does a currency hedge actually work?
- What is a forward contract?
- Should long-term investors hedge foreign equities?
- How do interest rates affect currencies?
Once you understand these relationships, international investing starts to look very different.
Learn More
The concepts and examples in this article are based on established principles of foreign-currency investing and currency risk.
CFA Institute
Currency Management — Foreign Exchange Risk and Investment Returns
Visit CFA Institute →Bank for International Settlements
Foreign exchange market and currency-related research
Visit BIS →